Yield volatility and measurement, Financial Management

Assignment Help:

Measuring volatility is very important as it is a critical input in valuation models. In subsequent chapters we will see the importance of assumed volatility in valuing bonds with embedded options. Also, in measuring the interest rate risk of a position, a combination of duration with yield volatility is used.

Measuring Historical Yield Volatility

Standard deviation or variance is used to measure the yield volatility. We can calculate variance using historical date with the help of the following formula:

         Variance =  508_yield volatility.png                                                                         ... Eq. (1)

and

         Standard deviation = 260_yield volatility1.png

In the above formula, Xt is the observation t of variable  448_yield volatility2.png  , is the sample mean for variable X, and T is the number of observations in the sample.

Our focus is to calculate the change in the daily yield relative to the previous day's yield.

This can be computed as the natural logarithm of the ratio of the yield for two days i.e.,                          

         ln (yt/yt - 1)

Where,

         yt      = Yield on day t.

         yt - 1  = Yield on day t - 1.

The relative change of daily yields computed under simple compounding and continuous compounding is almost same. But, continuous compounding is more popular among market participants.

Multiplying the natural logarithm of the ratio of the two yields by 100 scales gives us the percentage change in daily yields.

         Xt = 100 [ln (yt/yt - 1)]

Where,

         Xt   = % change in yield.

         yt    = Yield on day t.

         yt -  1 = Yield on day t - 1.

Determining the Number of Observations

The sample size, i.e., the number of observations taken, affects the calculation of daily standard deviation. It is difficult to define an ideal sample size as it always depends upon the situation in hand. For example, a portfolio manager who is more concerned about long-term volatility might use 25 days for observation whereas a trader concerned about overnight positions might use only 10 most recent trading days.

Annualizing the Standard Deviation

We can find the annualized standard deviation with the help of the formula given below:

         Daily standard deviation x 1126_standard deviation.png
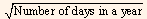
There is a different view regarding the number of days in the year that is to be used in the formula given above. Some market participants use 360 days whereas some use 365 days. There are some market participants who use only trading days i.e., 260 days based on five working days in a week for 52 weeks, while some other participants deduct 10 non-trading holidays too and use 250 days.

Interpreting the Standard Deviation

Assume that standard deviation for the 15 years zero coupon bond is 14%. If the prevailing yield is 8% then the annual standard deviation will be 112 basis points (14 x 8).              


Related Discussions:- Yield volatility and measurement

Assignmment, what is logical process modelling? what is physical modelling?...

what is logical process modelling? what is physical modelling?

OPERATING CYCLE, #discuss the applicability of operating cycle to poultry b...

#discuss the applicability of operating cycle to poultry business.

Determine the motivation foreign firm - high - tech u.s firm, Currently, ma...

Currently, many foreign firms from both developed and developing countries obtained high-tech U.S. firms. What might have motivated these firms to obtain U.S. firms? Answer: Se

Have large bank holding companies increased market share, Have the large ba...

Have the large bank holding companies increased their market share at the expense of smaller institutions? A: No. A study conducted by the Federal Reserve Bank of New York reve

Funds management, who are the participants in the hedge funds industries

who are the participants in the hedge funds industries

Constructing the theoretical spot rate curve for treasuries, The following ...

The following treasury issues can be included for the construction of the curve: On-the-run treasury issues. On-the-run treasury issues and sele

Geographical classification of mutual funds , Geographical Classification o...

Geographical Classification of Mutual Funds : Nations' boundaries provide territorial restrictions on the sale and purchase of mutual fund units or shares as is the case in com

Use of beta to partition risk, Use of Beta to Partition Risk The total ...

Use of Beta to Partition Risk The total risk or variability in earnings can be attributed to two classes of factors: Marketwide factors which create variability in all

Explain to tr, TR has recently been promoted to his first management positi...

TR has recently been promoted to his first management position. In the past, he very much enjoyed working as part of a team, but is having some difficulty in adapting to his new ro

Explain taxonomy of financial intermediaries, Taxonomy of financial interme...

Taxonomy of financial intermediaries We start by looking at the USA, the largest economy and financial system in the world. Subsequently we will turn to other countries. In the

Write Your Message!

Captcha
Free Assignment Quote

Assured A++ Grade

Get guaranteed satisfaction & time on delivery in every assignment order you paid with us! We ensure premium quality solution document along with free turntin report!

All rights reserved! Copyrights ©2019-2020 ExpertsMind IT Educational Pvt Ltd