Production with two variable inputs, Microeconomics

Assignment Help:

Production with Two Variable Inputs

*  There is relationship between productivity and production.

*  Long run production K& L are variable.

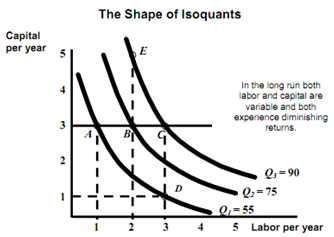
*  Isoquants analyze and compare different combinations of K & L and output
989_shape ofisoquants.png

Diminishing Marginal Rate of Substitution

- Reading Isoquant Model

 1)   Assume capital is 3 and labor increases from 0 to 1 to 2 to 3.  

- Notice output increases at decreasing rate (55, 20, 15) illustrating diminishing returns from labor in the short run and long-run.

2)    Assume that the labor is 3 and capital increases from 0 to 1 to 2 to 3.

- Output increases at the decreasing rate (55, 20, 15) because of diminishing returns from capital.

*  Substituting Among Inputs

- Managers want to determine the combination if inputs to use.  

- They should deal with the tradeoff between inputs.

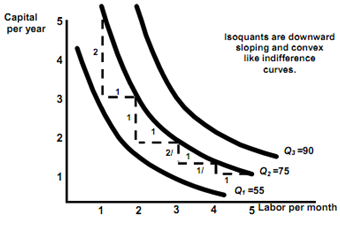
- The slope of each isoquant gives tradeoff between 2 inputs while keeping the output constant.

- The marginal rate(MR) of technical substitution can be given by:

Marginal Rate of Technical Substitution
1058_marginal rate of technical substitution.png

Observations:

1. Increasing labor in one unit increments from 1 to 5 results in a decreasing MRTS from 1 to 1/2.

2. Diminishing MRTS occurs because of diminishing returns and implies isoquants are convex. 


Related Discussions:- Production with two variable inputs

Draw a graph of the market for reserves, During summer of 2006, China incre...

During summer of 2006, China increased their reserve requirement for the banking system while maintaining a fixed target for the interbank lending interest rate. Draw a graph of th

What is utility maximization according to consumer behavior, What is utilit...

What is utility maximization according to consumer behavior? Consumer Behavior: Utility Maximization A foundational hypothesis onto individual behavior within modern econ

What is demand curve, Demand Curve The demand curve is a graph which pr...

Demand Curve The demand curve is a graph which presents the amount of a good that consumers are willing and able to buy at various prices. A normal demand curve is downward slo

Quantity demanded, What is the difference between change in quantity demand...

What is the difference between change in quantity demanded and change in demand

Monopolistic compitition, importance of monopolistc competition in Indian m...

importance of monopolistc competition in Indian market.

Three factors by america palce at world economy leading edge, 3 factors by ...

3 factors by america palce at world economy leading edge 3 factors have taken pride of place in explanations of America's place at the world economy's leading edge in its level

Elasticities of demand:, price of laptop increases by 20% and there is a 40...

price of laptop increases by 20% and there is a 40% drop in the quantity demanded?

Student, what are the sources of monopoly power

what are the sources of monopoly power

How have economists traditionally defined economic growth, How have economi...

How have economists traditionally defined "economic growth," and how is that different from "living standards growth"?  Economists have traditionally explained economic growth

Write Your Message!

Captcha
Free Assignment Quote

Assured A++ Grade

Get guaranteed satisfaction & time on delivery in every assignment order you paid with us! We ensure premium quality solution document along with free turntin report!

All rights reserved! Copyrights ©2019-2020 ExpertsMind IT Educational Pvt Ltd