Product differentiation, Microeconomics

Assignment Help:

Question: Product differentiation and entry/exit

Two differentiated goods, apples and oranges, are located at the two extremes of a linear product space (a segment of length 1) (i.e., apples at 0 and oranges at 1). The price of apples is p1, the price of oranges is p2. The utility of a consumer located at t that consumes one apple is

43_Product differentiation.png

The utility of a consumer located at t that consumes one orange is
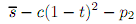
972_Product differentiation1.png

The utility of a consumer located at t that consumes nothing or both apples and oranges is zero. Consumers are located uniformly along the segment. (This is exactly like the transportation model, where spatial preferences are reinterpreted as tastes and 'transportation costs' are quadratic.). The unit cost of transportation is c. The marginal cost of each good is μ. Assume that Firm 1 is an apple monopoly, ?rm 2 is an orange monopoly.

(a) Calculate the demand functions for apples and oranges. For what ranges of prices the demands are well de?ned?

(b) Consider the demand functions for apples and oranges that you have calculated in the previous part. Assume that ?rms set prices simultaneously. Write the maximization problem of ?rm 1 and ?rm 2.

Solve for the Bertrand equilibrium. Compute prices, equilibrium quantity demanded and the pro?ts.

Suppose now that ?rm 1 is an apple monopoly, but that both ?rms produce oranges.

(c) Compute the equilibrium. Show that the pro?tof ?rm1issmaller(by a factor of4)than in part

(b). Explain step by step.

(d) Suppose that there are no exit costs, that entry costs are sunk, that ?rm1 is in bothmarkets,and that ?rm 2 is in the orange market (as in part (c)). Which ?rm has an incentive to exit the orange market? What do you conclude about the role of sunk costs or exit costs with regard to the possibility of entry deterrence through product differentiation (e.g., ?rm 1 entering ?rst in orange markets).


Related Discussions:- Product differentiation

Elasticities of supply and demand, ELASTICITIES OF SUPPLY AND DEMAND ...

ELASTICITIES OF SUPPLY AND DEMAND Usually, elasticity is a measure of the sensitivity of one variable to the other. It told us the percentage change in one variable in re

Elasticities and Price Controls, Suppose that two anti-marijuana proposals ...

Suppose that two anti-marijuana proposals are currently being debated in Congress. Proposal I will reduce the supply of marijuana and cause its price to rise by 7%. Proposal II wil

What is black marketing, What is black marketing?  Black Marketing mean...

What is black marketing?  Black Marketing means hoarding of sure commodity to sell it at higher prices. But it is an illegal activity in the economy and makes artificial shorta

Economics, 4) The prevention of major swings in economic activity can be ha...

4) The prevention of major swings in economic activity can be handled most easily by the A. household sector B. business sector C. financial sector D. government sector Explain

calculate total age specific death rate, 1. Definition: AGE-SPECIFIC D...

1. Definition: AGE-SPECIFIC DEATH RATE is the total number of deaths to residents of a specified age or age group in a specified geographic area (country, state, county, etc.)

What is economic efficiency, Q. What is Economic efficiency? Economic ef...

Q. What is Economic efficiency? Economic efficiency Explain a situation where the total value of the end uses, to which the resources are put, is maximised. A consequence is th

Cost function, what are the properties of cost function

what are the properties of cost function

What determines the price elasticity of demand, Question 1: i) Elaborat...

Question 1: i) Elaborate on the different types of price discrimination that a monopolist may use and what are the required preconditions for its application? ii) What dete

Marginal revenue function, Consider a market that is served by a single-pri...

Consider a market that is served by a single-price monopolist with marginal cost given by MC = $100 + Q. The market demand is given by P = $800 – 3Q. Determine the following: the f

Write Your Message!

Captcha
Free Assignment Quote

Assured A++ Grade

Get guaranteed satisfaction & time on delivery in every assignment order you paid with us! We ensure premium quality solution document along with free turntin report!

All rights reserved! Copyrights ©2019-2020 ExpertsMind IT Educational Pvt Ltd