Long run output, Managerial Economics

Assignment Help:

LONG RUN OUTPUT

In the LR whether or not the firm makes profit will depend on the conditions of entry.  For example, when surplus profits exist, there will be new entrants because they will make profit.

But as new firms enter, the market share enjoyed by each firm dwindles and their curves will shift to the Left.  The costs will also be affected by the new entrants in three ways:

1.          The new firms might make the cost resources to go up.

2.          The cost curves might also be unaffected.

3.          As new firms enter the cost curves might shift downwards because many sellers might force costs of resources downward.

But in the LR increasing costs are mostly likely.  If there are increasing costs then existing profits will be squeezed.  Because of the reduction in an individual firm's product, there will be a reduction in profits.

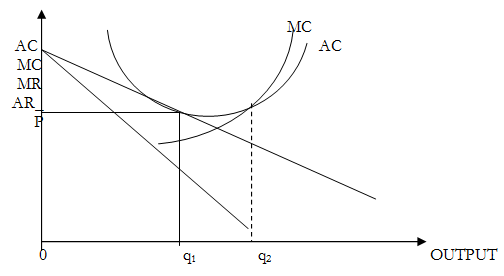
As long as there area profits in the industry, more firm's entry will stabilize when profits are ZERO. The losses might also cause exit of the firm's.  The incentive to withdraw ceases when losses have been eliminated.  Therefore the LR output and price of the firm looks like this:
2185_long run output.png

Zero profits imply that LRAC = LRAR. Therefore LRAC is tangent to AR at Q1.  But Q2 is the LR optimum output for the firm but with a negatively sloped AR curve.  Zero profits imply that each firm will utilize a scale of plant smaller than optimum.  Hence free entry leads to EXCESS capacity for each plant.


Related Discussions:- Long run output

Draw demand schedule and demand curve, The war on drugs is an expensive bat...

The war on drugs is an expensive battle, as a great deal of resources go into catching those who buy or sell illegal drugs on the black market, prosecuting them in court, and housi

Monopolistic practices, MONOPOLISTIC PRACTICES The following practices...

MONOPOLISTIC PRACTICES The following practices may be said to characterize monopolies. Exclusive dealing to supply and collective boycott Producers agree to supply onl

Cost of production and efficiency in long-run equilibrium, What are the con...

What are the conclusions about the cost of production and efficiency in the long-run equilibrium of a perfectly competitive industry? Three conclusions regarding the cost of pr

Monopolist advertise, A  monopolist has two types of customers. There are 1...

A  monopolist has two types of customers. There are 100 of Type A, who will every pay up to $10 for a single unit of the good, and 50 of Type B, who will every pay up to $8. Neithe

Break-even quantity., Bikes-for-two, Inc., produces tandem bicycles. Its co...

Bikes-for-two, Inc., produces tandem bicycles. Its costs have been analyzed as follows: VARIABLE COST Materials $30/unit Manufacturing labor 3 hours/unit ($8/hour) Assembly labor 1

The international monetary fund, The International Monetary Fund The I...

The International Monetary Fund The International Monetary Fund is a kind of an embryo World Central Bank.  Its objectives are: i.    To work towards the full convertibilit

Describe managerial and behavioural theories, Q. Describe Managerial and be...

Q. Describe Managerial and behavioural theories? It was only in 1960s that neo-classical theory of firm was disputed by alternatives like behavioural and managerial theories. M

Short run cost , What will be the table of total cost function?

What will be the table of total cost function?

Write Your Message!

Captcha
Free Assignment Quote

Assured A++ Grade

Get guaranteed satisfaction & time on delivery in every assignment order you paid with us! We ensure premium quality solution document along with free turntin report!

All rights reserved! Copyrights ©2019-2020 ExpertsMind IT Educational Pvt Ltd