Constructing the binomial interest rate tree, Financial Management

Assignment Help:

The fundamental principle is that when a tree is used to value an on-the-run issue, the resulting value should be arbitrage free i.e., it should be equal to the observed market value. Also, the interest rate tree should be consistent with the assumed interest rate volatility.

Let us, with help of an example, look at the process of constructing an interest rate tree:

The interest rate at the first node T would be the current 1-year on-the-run issue rate. The interest rate for year-one would be calculated using the coupon rate for the 2-year on-the-run issue, assumed interest rate volatility, and the interest rate at the base of the tree. Given these, the interest rates are determined on a trial and error basis. First, the lower rate r1,L at the node TL is assume and then using the formula (discussed earlier in this chapter) the interest rate at the higher value is calculated. It is then compared with the 2-year on-the-run issue to see if there are discrepancies in both the values; it implies that the assumption made is incorrect. If the value is too high, a higher rate guess should be made and if the value is too low a lower rate guess is to be made until the value of r1,L is in line with the 2-year on-the-run issue.

In similar manner, rates are determined for year-two - r2,LL, r2,HL and r 2,HH. The information required for this task includes:

  1. The coupon rate for the 3-year on-the-run issue.

  2. Assumed interest rate volatility.

  3. The interest rate at the base of the tree.

  4. The two 1-year rates (r1,L and r1,H).

A guess is made of the value r2,LL, and based on the formula discussed earlier in this chapter, the 

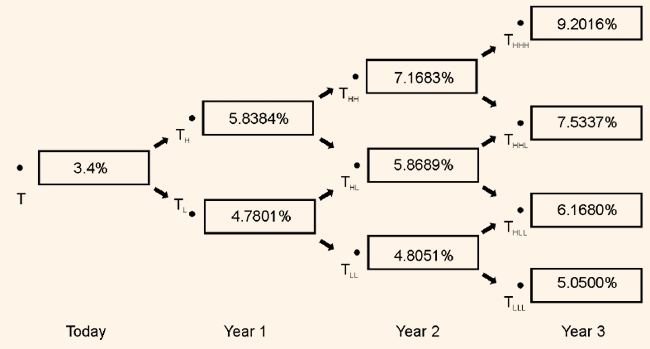
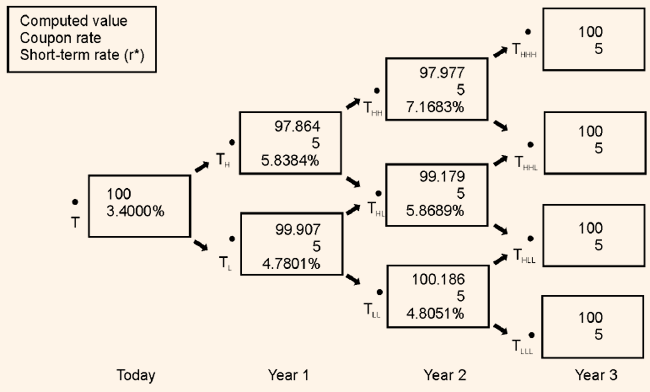
value of r2,HL and r 2,HH are calculated. If the value generated by this process is not equal to the market value of the 3-year on-the-run issue, the process is to be repeated again. An iterative process is again followed. Table 2 shows the binomial interest rate tree for the issuer for valuing issues up to four years of maturity assumption volatility for the 1-year rate of 10% and Table 2 verifies that the rates on the binomial interest rate tree are the correct values. This is arrived at by showing that when the 3-year on-the-run issue is valued using backward induction method the value is 100, which is nothing but the market value of the 3-year on-the-run issue.

Table 2: Binomial Interest Rate Tree
355_binomial interest rate tree1.png

Assumed Volatility = 10%

Table 2: Verification of the Rates on the Binomial Interest Rate Tree
638_binomial interest rate tree.png


Assumed Volatility = 10%

Coupon tate = 5%


Related Discussions:- Constructing the binomial interest rate tree

Proposed pollution control project -memorandum, Memorandum Memo to: Bla...

Memorandum Memo to: Blackwater plc Main Board. Subject: Proposed Pollution Control Project. From: Lower down the hierarchy. Date: That'll be the day. On purely non-

Which parameter better calculates value creation, Which parameter better ca...

Which parameter better calculates value creation; the EVA (Economic Value Added), the economic profit or the CVA (Cash Value Added)? The EVA (Economic Value Added) is the profi

Illustrate the steps of creative accounting, Illustrate the steps of Creati...

Illustrate the steps of Creative accounting Creative accounting include: 1 Timing of transactions. Delaying or hurrying up the despatch of invoices at the yearend to decr

Leverage, What are the importance of leverage on a small scale firm?

What are the importance of leverage on a small scale firm?

Determine the change in profit, (a) The BEQ is 200 customers per month, i.e...

(a) The BEQ is 200 customers per month, i.e. $3,000 / ($20 - $5) (b) The margin of safety is 300 customers, i.e. 500 - 200 (c) Graph (d) New break-even is 334 customers, i

Finance, a recent business school graduate, you work directly for the corpo...

a recent business school graduate, you work directly for the corporate treasurer. Your corporation is going to issue a new security plan and is concerned with the probable flotatio

Compare and contrast a forward contract and an option, QUESTION (a) Bri...

QUESTION (a) Briefly define foreign exchange rate risk and the three different types of exchange rate risks (b) Identify and outline the different methods of internal and ex

Debt securities, Fixed income security is a financial obligation of an ...

Fixed income security is a financial obligation of an entity, which promises to pay a pre-specified amount of money at per-specified date. Debt securities (

Calculate the standard deviation of a portfolio , Aquaman stock has exhibit...

Aquaman stock has exhibited a standard deviation in returns of 0.7, whereas Green Lantern stock has exhibited a standard deviation of 0.8. The correlation coefficient between the

Define pro forma financial statements and cash budget, What is the differen...

What is the difference among pro forma financial statements and a cash budget?  Explain why pro forma financial statements are not employed to forecast cash needs. Pro forma inco

Write Your Message!

Captcha
Free Assignment Quote

Assured A++ Grade

Get guaranteed satisfaction & time on delivery in every assignment order you paid with us! We ensure premium quality solution document along with free turntin report!

All rights reserved! Copyrights ©2019-2020 ExpertsMind IT Educational Pvt Ltd