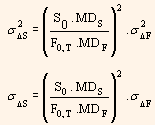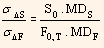Computing hedge ratio: the modified duration method, Financial Management

Assignment Help:

Let us consider a situation wherein a position in an interest rate dependent asset such as a bond portfolio or a money market security is hedged by using an interest rate futures contract.

Let us assume that the change in the yield ?y, will be same for all maturities, i.e., only parallel shifts in the yield curve can occur. From the modified duration definition, we have,
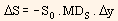
         1187_hedge ratio.png

We can also say that to a reasonable approximation, it is also true that,
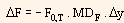
         1584_hedge ratio1.png

In the first equation, S0 represents value (decimal form) of the asset that is being hedged and MDS  represents modified duration of the asset. In the second equation, F0,T represents quoted price in decimals for the interest rate futures contract and MDF  represents modified duration of the asset underlying the futures contract (i.e., modified  duration of the cheapest to deliver bond).

As ?y is assumed to be the same for all maturities, we have ρΔSΔF = 1.  By combining first and second equation, we get,
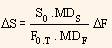
         10_hedge ratio2.png

This can be written as,

         1520_hedge ratio3.png

Thus, we get,  

         1239_hedge ratio4.png

Finally, the optimal Hedge Ratio (HR) is used for hedging 
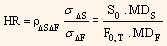
         1593_hedge ratio5.png

By using this equation we can equate the duration of the combined position equal to zero.

However, the hedge obtained using the above equation is not perfect because of following reasons:

  • It assumes that ?y is same for all yields. But, in reality short-term yields are generally more volatile and also have low correlation with long-term yields. Consequently, the performance of the hedge will not be appreciable, particularly when there is large variation between MDS and MDF.

  • It does not consider convexity. In case the convexity of the asset underlying the futures contract is remarkably different from the convexity of the asset being hedged, and at the same time if there is large difference in interest rates, then the performance hedge will be worse than is expected.

  • An assumption with regard to cheapest-to-deliver bond is essential to compute MDF. If the cheapest-to-deliver bond changes, then MDF   as well as optimal number of contracts also changes.

Now, as we know the hedge ratio, let us see the number of futures contracts to be purchased. We have earlier studied that the number of futures contracts required is given as
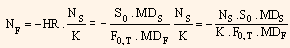
         651_hedge ratio6.png

In the above equation, NS indicates the number of units of spot asset to be hedged and k indicates the contract size.

We can estimate hedge ratio by using regression also. It can be interpreted as follows:
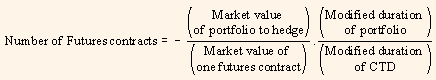
         1552_hedge ratio7.png

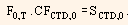
We have earlier studied that,  210_hedge ratio8.png   Here  2120_hedge ratio9.png   represents conversion factor of the cheapest to deliver bond at time 0 and SCTD,0  represents its price. If we replace F0,T in the above formula, we get,
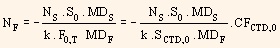
         569_hedge ratio10.png

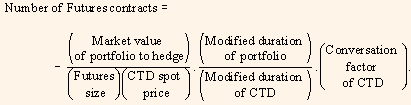
This can be interpreted as follows:

1461_hedge ratio11.png


Related Discussions:- Computing hedge ratio: the modified duration method

Which ratios would a banker be most interested, Which ratios would a banker...

Which ratios would a banker be most interested in when considering whether to approve an application for a short-term business loan? Explain. Bankers and another lenders use li

Calculation of a firms sales returns, a) The combined two-firm concentratio...

a) The combined two-firm concentration ratio of Motorola (approximately 17.5%) and Nokia (35%) is around 52.5% of the market. b) Up to 2 marks for correct definition: Market sha

Cost of capital.., your firm is considering its household products division...

your firm is considering its household products division. you identify John Lewis as a firm with comparable investments. suppose J.L. equity has a market capitalization of 150 bill

APPLICABILITY OF OPERATING CYCLE, #questioDiscuss the applicability of an o...

#questioDiscuss the applicability of an operating cycle in the vegetable growing business n..

Introduction of just-in-time inventory management, Q. Introduction of just-...

Q. Introduction of just-in-time inventory management? It has already been observe that a reduction in inventory due to the introduction of just-in-time inventory management ca

IFM, 38. The optimum capital structure is the one with i) highest value of ...

38. The optimum capital structure is the one with i) highest value of the firm ii) Lowest value of the firm iii) highest shares in numbers iv) highest debt

Remaining differences with us gaap, Remaining differences with US GAAP ...

Remaining differences with US GAAP IFRS 8 comprise intangible assets as part of the non-current assets. SFAS 131 only refers to tangible assets. IFRS 8 requires method

Why is the replacement value of assets method, Why is the replacement value...

Why is the replacement value of assets method not generally used to value complete businesses? The replacement value of assets method isn't often applied to entire business val

Case study.., This case has been framed in order to test the skills in eval...

This case has been framed in order to test the skills in evaluating a credit request and reaching a correct decision. Perluence International is large manufacturer of petroleum and

Accept-reject rule, Accept-Reject Rule: The decision rule is to accept ...

Accept-Reject Rule: The decision rule is to accept the project if the computed payback period is less than the standard.  If not, reject it.  While ranking the projects, projec

Write Your Message!

Captcha
Free Assignment Quote

Assured A++ Grade

Get guaranteed satisfaction & time on delivery in every assignment order you paid with us! We ensure premium quality solution document along with free turntin report!

All rights reserved! Copyrights ©2019-2020 ExpertsMind IT Educational Pvt Ltd